A Seller's Guide

Avoiding Foreclosure

The full ladder of options, climbed in order — what each one is, who it fits, and why the first step is smaller than you fear.

This guide reads like a book. Every page is the same fixed size, the content reflows to fill each page, and the page count adjusts automatically. Turn the pages with the arrows or your keyboard, swipe on touchscreens, or jump straight to any page from the table of contents below.

Avoiding Foreclosure, presented as a fixed-size paginated book

Page 1

A Seller's Guide

Free Guide

Avoiding Foreclosure

The full ladder of options, climbed in order — what each one is, who it fits, and why the first step is smaller than you fear.

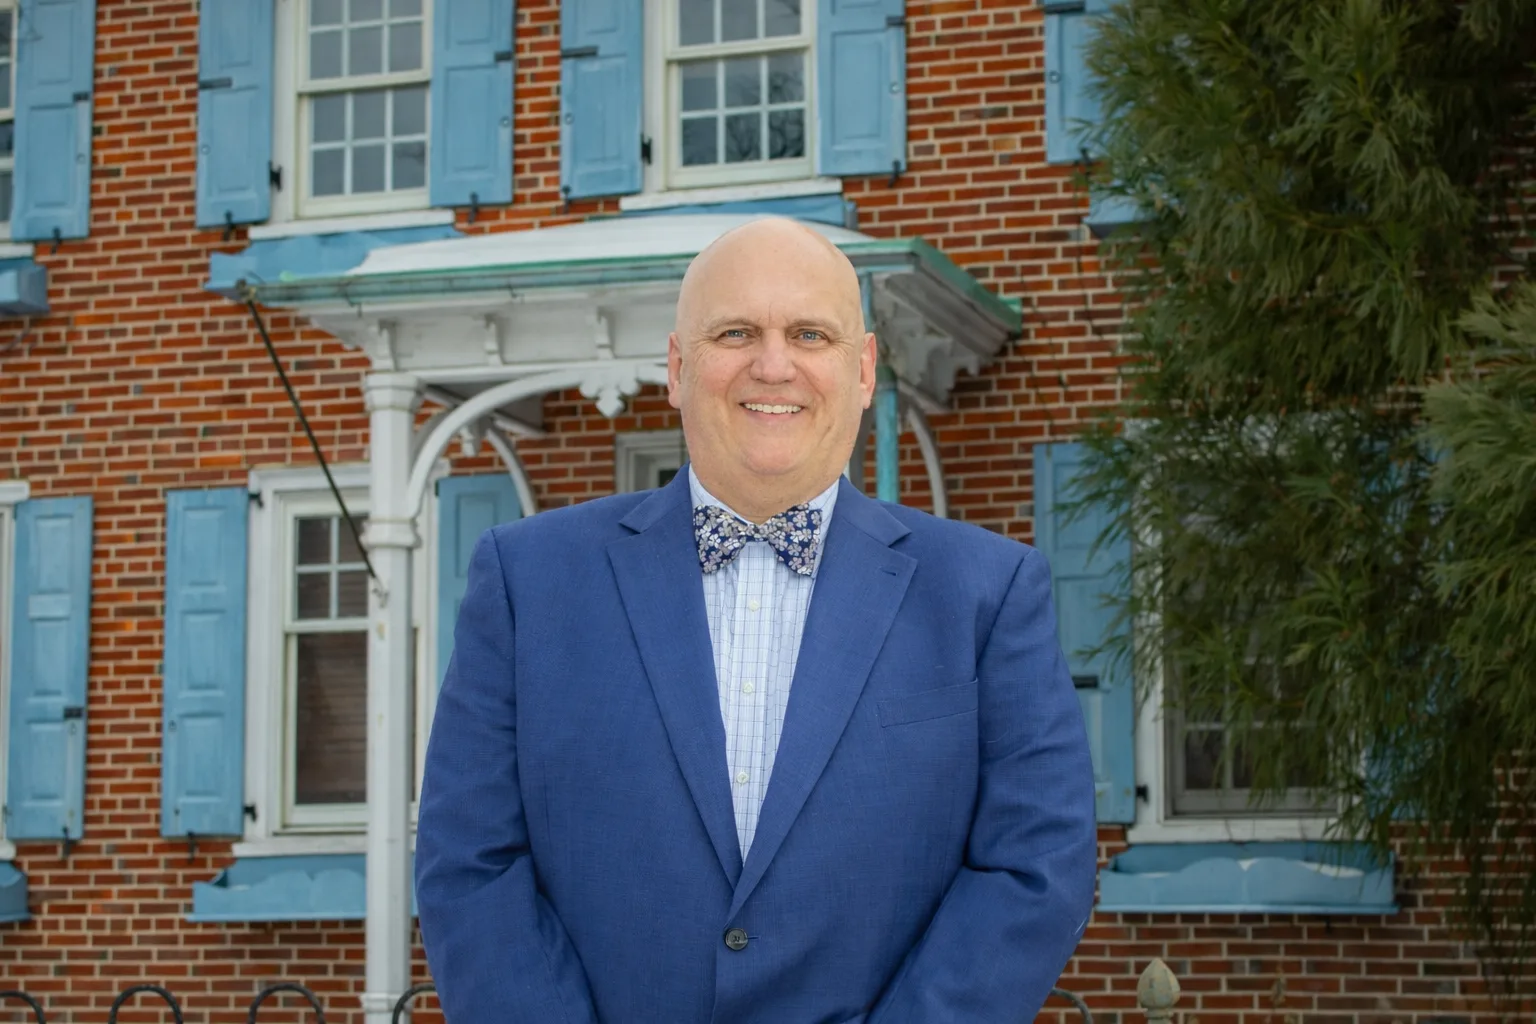
Bob Millaway, Epique Realty agent A.I. Certified Agent badge
Epique Realty

Robert "Bob" Millaway, REALTOR® | Epique Realty

South Jersey | robertmillaway.com | (856) 426-1522

A Note Before We Start

If you are reading this guide at a kitchen table in Burlington or Camden County with a stack of unopened envelopes beside it, I want to start where my companion guide Short Sales, Explained Plainly starts, because it is the truest sentence in either of them: falling behind on a mortgage is a math problem with a calendar attached. It is not a verdict on your character.

I have sat at those tables. The people across from me were not careless. They were careful people whose arithmetic broke — a job that ended, hours that shrank, a medical bill with its own gravity, a marriage that became two households on one income. Life changed the numbers first. The missed payments are just where the change became visible.

What I can offer you here is the map. There is a ladder of options between 'behind on payments' and 'foreclosure,' and it is taller than most homeowners are ever told — but the rungs are climbed in an order, and the order matters, because the earlier rungs are the gentlest and they do not stay available forever. This guide walks the whole ladder: what each option actually is, who it fits, and what it asks of you. My companion guide Short Sales, Explained Plainly goes deep on one rung in particular; this one keeps the whole staircase in view.

Two things about my role, said plainly. I am a REALTOR®, not an attorney, not a tax professional, and not a financial advisor. Several rungs on this ladder are legal territory, and this guide will keep handing you to the people whose territory it is. And nothing here is a promise: every rung that keeps you in the home is your lender's decision to grant, not yours to claim. What I can promise is that the options are real, the sequence is learnable, and the first step is smaller than you fear.

My philosophy in every transaction is calm over chaos — and calm, in this situation, is not a mood. It is a method: open the mail, make the call, work the ladder in order.

— Bob

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 2

Before the Ladder

1 Two Truths Before the Ladder

Everything in this guide hangs on two truths. They are not comforting in the greeting-card sense, but homeowners who absorb them early do better than homeowners who learn them late.

Truth one: time is the asset. When a household falls behind, what it actually owns — more than equity, more than leverage — is time, and time is what the options are made of. The gentle rungs at the bottom of the ladder exist while the problem is young. As notices pile up and the file hardens, rungs fall away — not all at once, and not on a schedule anyone can print in a guide, but steadily. This is not a threat and it is not a sales line. It is the mechanics of the situation, and it produces the single most useful sentence in this guide: earlier gives you more rungs. Whatever you do, do it while the ladder is still tall.

Truth two: silence is the only strategy that never works. The instinct is understandable — the envelopes are frightening, the phone number on the statement feels like a collections desk, and not opening either one buys a quiet evening. But understand what silence looks like from the other side of the table: a file with no contact, no explanation, and no plan is a file that moves in only one direction. Lenders maintain entire departments — loss mitigation, in their language — whose work is reviewing exactly your situation, because a loan that gets worked out can be a better outcome for the lender than a foreclosure is. That is mutual interest, stated plainly. It is not kindness, and it is not a promise that your request will be granted. It is simply true that the conversation is the doorway to every rung that follows, and avoidance is the doorway to none of them.

Silence is the only strategy that has never worked. Every rung on this ladder starts with the same two moves: open the mail, and make the call.

So the first step is not a rung at all. It is this: gather every notice you have received, opened or not, and call the number on your mortgage statement — the servicer, the company that collects your payment — and say the plain sentence: 'I'm having trouble with my payment, and I want to know my options.' You are not confessing. You are opening a file that already exists, on purpose, while it can still be shaped.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 3

The Keeping-the-Home Rungs

2 Rung One — Forbearance: A Pause, Not a Forgiveness

The first rung is the one built for a problem that is real but temporary.

A pause is meant to protect the home while life steadies. The house stays yours while it does.

Forbearance is an agreement with your servicer to pause your payments, or reduce them, while a hardship passes. A job loss with a new position already lined up. An illness with a recovery on the horizon. A short, defined gap between the life you had and the life that is about to resume. For that shape of problem, forbearance is the ladder's gentlest rung: the home stays yours, the loan stays in place, and the crisis gets room to end.

Here is the part that must be understood before anything is agreed, because it is the part that surprises people later: the payments are not forgiven. They are moved. Every paused or reduced payment goes somewhere — and where it goes is decided by the agreement, not by assumption. So the essential act of accepting a forbearance is reading, or having read to you and explained, exactly where the moved payments land when the pause ends: whether they come due, and in what arrangement, under the terms you are accepting. Get that answer in writing, and keep the writing. If the document does not say where the payments go, the question has not been answered yet.

Forbearance fits a hardship with an end in sight. If nothing about your income is going to change — if the gap is not a bridge but the new landscape — a pause alone will deliver you to the far side of the pause with the same arithmetic waiting. That household belongs on the next rungs, and there is no shame in skipping ahead. The ladder is not a test you can fail. It is a set of doors, and the honest question at each one is only: does this fit the shape of my problem?

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 4

The Keeping-the-Home Rungs

3 Rung Two — Repayment Plan: Catching Up in Slices

The second rung is for the household whose emergency has ended but whose arrears remain.

A repayment plan spreads what you missed across your coming payments. You resume your regular payment, with an added portion on top that retires the missed amount piece by piece, until the loan stands current again. Nothing about the loan itself changes — not its terms, not its length. Only the catching-up is structured, in an agreement, instead of left to hope and overtime.

The fit is specific, and naming it honestly is a kindness: this rung is for income that is back. The job resumed, the hours returned, the second income restarted — the household can carry its normal payment and something more. If the income has not returned, a repayment plan is an agreement to fall behind on a schedule, and it helps no one to sign it. Lenders know this, which is why the conversation at this rung is really an arithmetic review: what comes in, what goes out, and whether the added portion is sustainable in the real month rather than the optimistic one.

Do that arithmetic honestly before you agree to it. A plan you can keep is a rung climbed. A plan built on a best-case month collapses into a worse position than an honest 'not yet' at the rung below — because now there is a broken agreement in the file as well as a balance. Calm over chaos applies to paperwork too: the sustainable plan, plainly stated, beats the heroic one.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 5

The Keeping-the-Home Rungs

4 Rung Three — Loan Modification: Rewriting the Loan Itself

When the change in your life is not temporary — when the income that returns will return smaller, or the household that pays the mortgage is permanently a different household — the first two rungs are bridges to a destination that no longer exists. The third rung addresses the loan itself.

A loan modification is a restructuring of your existing loan: the lender adjusts the loan's terms, by the lender's own calculations, so that the payment fits the household you actually have now. The loan is not replaced and the home is not sold. The terms are rewritten — how, and by how much, is the lender's decision, made from your documented finances, and it cannot be promised by anyone in advance. What you are submitting is an application, with the same species of paper life the Short Sale guide describes: income, expenses, hardship, the whole honest picture, because the lender will only rewrite a loan it can see whole.

One feature of this rung deserves a plain explanation, because it confuses people into thinking something has gone wrong: you may be asked to prove the new payment works for a stretch first. Before making a modification permanent, a lender may set the adjusted payment on a provisional basis and watch whether the household can actually carry it. That is not a trick and not a rejection — it is the lender testing the plan before signing it, the way you would. Treat that stretch as what it is: the audition for the new loan. Payments made exactly as agreed, exactly when agreed, are the entire argument.

A modification is the deepest of the keeping-the-home rungs, and the most document-heavy. It rewards the same disciplines as everything else in this territory: a complete file, a consistent story, and responses that arrive when they are asked for. A HUD-approved housing counselor — a category of advisor that exists specifically for this work, explained on the legitimate-help shelf in Section 10 — can help you assemble that file and understand what the servicer is asking for. However you climb this rung, climb it with your eyes on the same truth as all the others: it is granted, not claimed.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 6

The Keeping-the-Home Rungs

5 Rung Four — Refinance: The Narrow Door

Every options list in this territory includes refinancing, and honest guides owe you the fence around it rather than a paragraph of padding.

A refinance replaces your current loan with a new one, on new terms. In ordinary times, for a household in good standing, it is a routine tool. For the audience of this guide, the door is narrow, and here is why, stated once and plainly: a new loan must be underwritten, which means it is extended to households whose current income, current record of payments, and remaining equity support it. A household already behind on the loan it has will rarely present the picture a new lender requires, and a home worth less than its loan offers no room for a new one to stand in.

So this rung is short because the truth is short. If your hardship is recent, your payments are strained but not yet broken, and meaningful equity remains, the question is worth one honest conversation with a lender — who will tell you, from your actual file, whether the door is open. If you are already well behind, do not spend your time or your hope here. The ladder has rungs built for you. They are the ones above and below this one, and your energy belongs on them.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 7

The Exit Rungs

6 Rung Five — Sell the Home on Your Own Terms

At some point on the ladder, the honest question changes. The rungs so far ask how do I keep this home? This rung asks the question that, for many households, turns out to be the strongest one available: what if I sell it myself, while the selling is still my choice?

A sale you initiate runs on your timeline. That is what makes this rung the strongest one on the ladder.

If equity remains in your home — if it would sell for more than the loan and the costs of selling — a conventional sale is the most powerful option on this entire ladder. It requires no lender's permission. It runs on your timeline rather than a department's. It converts the home into the money that settles the loan in full, ends the monthly pressure permanently, and lets you choose your next housing with what remains instead of having it chosen under duress. Homeowners in distress sometimes assume they are underwater when they are not; a real valuation therefore comes before this rung is ruled out — and my guide 6 Questions to Ask Before You Sell is built to walk exactly that decision, question by question.

Understand what distinguishes this rung from its neighbors: control. A sale you initiate, priced and presented properly, marketed to every buyer at once — the process my guide Selling Your Home in South Jersey walks from first decision to closing day — reaches outcomes that no distressed process can match, because none of it is negotiated from a file marked behind. Selling is not surrender. For the household with equity and a payment that no longer fits its life, selling is the exit that keeps the most money, the most dignity, and the most future intact.

If the valuation comes back the other way — the home worth less than the loan — the next rung is the one built for precisely that arithmetic.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 8

The Exit Rungs

7 Rung Six — Short Sale: Selling With the Lender's Permission

A short sale is a sale in which your lender agrees to accept what the home actually brings as the settlement of a larger loan. You list the home, a real buyer offers, and the lender — the party absorbing the difference — reviews your documented hardship and the offer, and decides whether the sale may proceed and on what terms. It is a real sale with one extra party whose permission governs everything.

That is the whole of it here, deliberately. The mechanics — the hardship file, the approval letter, the remaining-balance question that must be answered in writing, the buyer's patience problem, the liens that complicate it — deserve more than a paragraph, and they have it: my companion guide Short Sales, Explained Plainly teaches this rung in full, and it is the next thing to read if this is where your ladder leads.

Here, in the ladder's own terms, only its place needs fixing: the short sale sits between selling with equity and surrendering the deed. It fits the household that is underwater, has a genuine and documentable hardship, and needs to move on — and like every rung in this guide, it is the lender's to grant, never yours to claim, and never anyone's to guarantee.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 9

The Exit Rungs

8 Rung Seven — Deed in Lieu: Handing Back the Keys by Agreement

The last of the exit rungs is the simplest in shape and the one most in need of a lawyer's eyes before it is touched.

A deed in lieu of foreclosure is an agreement in which you transfer the home to the lender, and the lender accepts the deed instead of pursuing the foreclosure process. No listing, no buyer, no sale. The keys change hands by agreement rather than by judgment. It exists. For a household that has climbed the earlier rungs honestly and found them closed — no equity for a sale, no approval for a short sale, no modification granted — it can be a quieter ending than the alternative in the next section.

Three cautions, each of them a reason this rung is climbed with counsel and never alone. First, it is the lender's choice, entirely — a lender may decline the deed, and circumstances like additional liens on the home can make acceptance unlikely, because the lender would be taking the property with those claims attached. Second, and most important: the question of any remaining balance — what happens to the difference between what you owed and what the home is worth — must be settled in the agreement itself, in writing, before anything is signed. That is a legal question with consequences that outlive the house, and it belongs to your attorney to raise, to read, and to answer from your actual document. Do not let this rung be described to you as clean until your attorney has read the paper and used that word. Third, never confuse this agreement with the predators' version of it in Section 10: transferring your deed to your lender, in a documented agreement your attorney has reviewed, is a legal instrument. Signing your deed over to a helper is the most dangerous move in this entire territory. The difference is everything.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 10

If It Goes the Distance

9 If Foreclosure Comes Anyway

Some ladders are climbed to the top. This section is for the household that reaches this rung anyway — and it is written calmly, because calm is what is useful here.

Foreclosure is a legal process. In New Jersey, it runs through the courts — and the timelines, the procedures, and what any particular notice requires of you are your attorney's territory, which is stated once here and governs everything this section does not say. What a guide can honestly tell you is the shape of your part in it: the process moves through stages, notices arrive at those stages, and a homeowner who is present in the process — who opens the notices, responds through counsel, and appears where appearance is required — is in a materially different position from one whose file shows only absence. Showing up does not guarantee an outcome. Nothing in this territory carries a guarantee. But outcomes in a process with human decision-makers are influenced by the record in front of them, and a record of engagement is a different record than a record of silence. If cost is the barrier to counsel, say so early and out loud — legal aid organizations and HUD-approved housing counselors exist in part to connect homeowners in this exact position with help they can reach.

One adjacent subject belongs in this section because frightened homeowners ask about it, and it deserves an honest boundary rather than a lesson: bankruptcy. It is a legal proceeding with its own rules, its own consequences, and its own specialists. Whether it belongs in your situation is a question only a bankruptcy attorney can answer from your full financial picture — no real estate guide can, and this one will not try. If the word has entered your thinking, the correct next step is that consultation, not a chapter.

And then, the part nobody prints and everybody in this position deserves to hear: there is a life after this section. A foreclosure on a record is an event, not an identity, and it is not the end of a family's housing story. People rebuild — in an order, the way everything in this guide happens in an order. First, stable housing: a roof that fits the new arithmetic, chosen calmly rather than grabbed in panic. Then, records: the slow, unglamorous work of paying what remains on time, every time, until the recent past is no longer the whole story. Then, time: the ingredient no one can sell you and no one can take from you, which does quiet, compounding work on every record it touches. I have watched households come through the far side of this and buy again, in these same counties, in homes that fit the lives they actually had. That is not false cheer, and it is not a timeline. It is simply the observed truth that this chapter, however heavy, is a chapter.
Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 11

Know Who to Trust

10 The Scam Shelf — and the Legitimate Shelf

Financial distress attracts a particular species of business, and it advertises exactly where frightened homeowners look. My guides Short Sales, Explained Plainly and Should You Sell Your Home Fast for Cash? carry this warning in neighboring fields; it belongs here in full, because this guide's audience is the predators' exact target.

Learn the shapes on the scam shelf:

  • Foreclosure-rescue fees. Anyone who asks you to pay — especially in advance — for stopping a foreclosure or negotiating with your lender is showing you their business model: your fee. The negotiation that matters starts free, with your own servicer and the counselors below. Do not pay to open a door that is already unlocked.

  • 'We buy your home and rent it back.' The deed scheme in its friendliest costume: you sign the home over, stay on as a renter, and the helper fixes everything. The fixing rarely materializes. The deed, however, has moved — and with it, nearly every right you had. Never sign your deed to a helper. Ever.

  • 'Stop talking to your lender — and send your payments to us.' Anyone who instructs you to cut off your servicer, or to redirect your mortgage payments to them, is dismantling your position for their benefit. Your servicer is the counterparty to every real rung on the ladder. Instructions to go silent — the one strategy that never works — are a confession about who the silence serves.

  • Guarantees. Every rung in this guide is a lender's decision or a court's process. Anyone who guarantees you an outcome from either is promising something that is not theirs to give. The guarantee is the tell.

And the legitimate shelf, which is easy to recognize because nothing on it asks for your deed, an upfront rescue fee, or your silence:

  • Your own real estate attorney — the only person in the room whose job is solely your legal position, and the proper reader of everything in Sections 8 and 9.

  • A HUD-approved housing counselor — advisors approved through the federal housing department exist specifically to work with distressed homeowners, reviewing the whole ladder against your real numbers, typically at little or no cost. If a 'counselor' asks for a large upfront fee, you are back on the wrong shelf.

  • Your servicer's loss-mitigation department — the counter across the table. Treat it as a negotiating party: approached with your file complete, your facts straight, and your counselor or attorney informed — not as a rescue line, and never as an enemy to be avoided.

  • Your agent — for the rungs that are sales. A real valuation is what tells you whether Rung Five is open, and experience with distressed sales is what Rung Six runs on.

A legitimate helper can always survive you taking time to verify them. Urgency is the predator's favorite tool, in this field above all others.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 12

Your Own Discipline

11 The Folder: One Place for Every Piece of Paper

The Short Sale guide teaches the lender's file — the hardship package a short sale runs on — and this guide will not repeat that lesson. What belongs here is the household's own discipline, and it is a single habit with outsized returns: one folder.

One folder: every notice, every agreement, every name and date from every call.

Every notice that arrives, opened. Every letter from the servicer. Every agreement the moment it is signed — especially anything from Sections 2 through 4, where what was promised lives only in the writing. And a running log of the human side of the process: every call, with the date, the name of the person you spoke with, and in a line or two, what was said and what was promised. Names and dates, written down while they are fresh.

This sounds like clerical advice. It is actually leverage. In a process run through departments and queues, your folder is the only continuous memory your case has — servicers transfer files, representatives rotate, and the household that can say who said what, and produce the letter that says it too, is a household whose file gets handled with care. Should your situation reach an attorney's desk, the folder is the first thing that attorney will ask for, and the difference between a complete one and a shoebox of recollections is measured in what can actually be done for you.

One folder. Every notice, every name, every date. It is the cheapest rung on the whole ladder, and you can build it tonight.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 13

Which Rung Fits Your Situation

12 The Ladder on One Page

Read the situations honestly. The rung that fits is the one whose description matches your life as it is — not as it was, and not as you hope it feels by spring.

The Keeping-the-Home Rungs

  • My hardship is temporary and its end is visible — the job, the recovery, the resumed income is coming: start with forbearance, and get where the moved payments go in writing.

  • My income is back, and I can carry my payment plus something more: ask about a repayment plan, and do the arithmetic honestly first.

  • My circumstances have changed for good, and I need the loan itself to change: apply for a loan modification, with a complete file — and treat any provisional stretch as the audition it is.

  • My payments are strained but current, and real equity remains: refinancing is worth one honest lender conversation — and no more hope than that.

The Exit Rungs

  • A real valuation says my home is worth more than the loan and selling costs: sell conventionally, on my own timeline — the strongest rung on the ladder.

  • I am underwater, with a genuine hardship, and I need to move on: read Short Sales, Explained Plainly and assemble the file.

  • The sale rungs are closed and my attorney has read the paper: a deed in lieu may be the quieter ending — with the remaining-balance question settled in the agreement, in writing, first.

At Every Rung

  • I have opened every notice and started the folder — every letter, every name, every date.

  • I have called my servicer and said the plain sentence: I am having trouble, and I want to know my options.

  • I have a HUD-approved housing counselor or my own attorney reviewing the ladder against my real numbers.

  • Nobody helping me has asked for my deed, an upfront rescue fee, my silence, or my payments — and nobody has guaranteed me an outcome.

  • If notices have become court papers, I have counsel, and I am showing up rather than absenting myself.

Wherever you honestly land on this page, that rung is your next conversation — with your servicer, your counselor, your attorney, or your agent. Not all of them. The next one.

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 14

The Last Word

A Final Word

If you take one thing from this guide, let it be the shape of it: there is a ladder, it is taller than you were told, and it is climbed in order — one honest rung at a time, starting with a phone call you can make before this day is out.

None of the rungs are guaranteed, and I have not pretended otherwise anywhere in these pages, because you are owed better than a brochure at a moment like this. But every rung is real, every one of them has carried South Jersey households out of exactly the arithmetic you are facing, and the households that come through best share one trait that has nothing to do with money: they started. They opened the mail. They made the call. They climbed from where they actually were instead of waiting to feel ready.

You deserve advice that works for you rather than for the person giving it. Start with the conversation — with your servicer, with a counselor, with an attorney, or with me. Bring the folder. We will lay the ladder out in order, calmly, and you will decide which rung is yours.

Ready when you are

Robert 'Bob' Millaway · REALTOR® · Epique Realty · bob@robertmillaway.com · (856) 426-1522 · License #791082, NJ

The information in this guide is general education, not legal, tax, or financial advice. Avoiding foreclosure involves legal and financial questions — including what any agreement means for any remaining balance, and how any outcome is treated at tax time — that only your own professionals can answer from your actual documents. Consult a qualified real estate attorney and a CPA about your specific situation, and consider a HUD-approved housing counselor, who can review your full range of options, before signing anything or agreeing to any terms. Every option described here is subject to your lender's or servicer's approval, and none is guaranteed. If your property is currently listed with a REALTOR® or broker, please disregard this guide — it is not intended to solicit other brokers' listings. Information deemed reliable but not guaranteed.

Equal Housing Opportunity logo

Equal Housing Opportunity

Robert Millaway · Epique Realty · (856) 426-1522 · robertmillaway.com 15

Arrow keys to turn pages

Swipe left or right to turn pages

Take It With You

Get the Whole Guide as a PDF

The complete guide, ready to read on any device, print, or share. The reader-friendly PDF opens in a new tab.

Download the Full PDF

Opens the full reader-friendly PDF in a new tab.